You may think that placing the same commercial account with two collection agencies at once will improve your odds of collecting. The idea may seem reasonable at first, and the best way to judge it is to follow one account from placement all the way to payment and count the headaches it can create along the way.
When two agencies work the same commercial account, the creditor risks conflicting payment terms and competing commission claims, and the debtor gets a reason to wait until someone sorts out who has authority. No general federal rule prohibits the arrangement, but state law or your agency agreements may restrict it, and a written recall before reassigning the account is usually the cleaner path.
The Case for Two Agencies
Picture a $20,000 invoice that has sat with one agency for four months. The agency has sent letters and made calls, and the debtor has stopped answering. You are paying nothing, since the fee is contingent, but you are also collecting nothing.
Then another agency comes along, maybe offering a lower rate. The first agency is still working the account, but after four months of silence it seems reasonable to ask why you shouldn't give someone else a shot. You place the account with the second agency too, and now two agencies are working the same balance.
A fresh set of eyes might find a phone number the first agency missed or reach the decision-maker who has been dodging calls. Since the fee is contingent, the second agency costs nothing up front, so on paper you have doubled your chances for free.
Follow the Account Into the Debtor's Office
Both agencies call within the same week. Suppose the second agency's fresh approach works, and the debtor decides to deal with the balance.
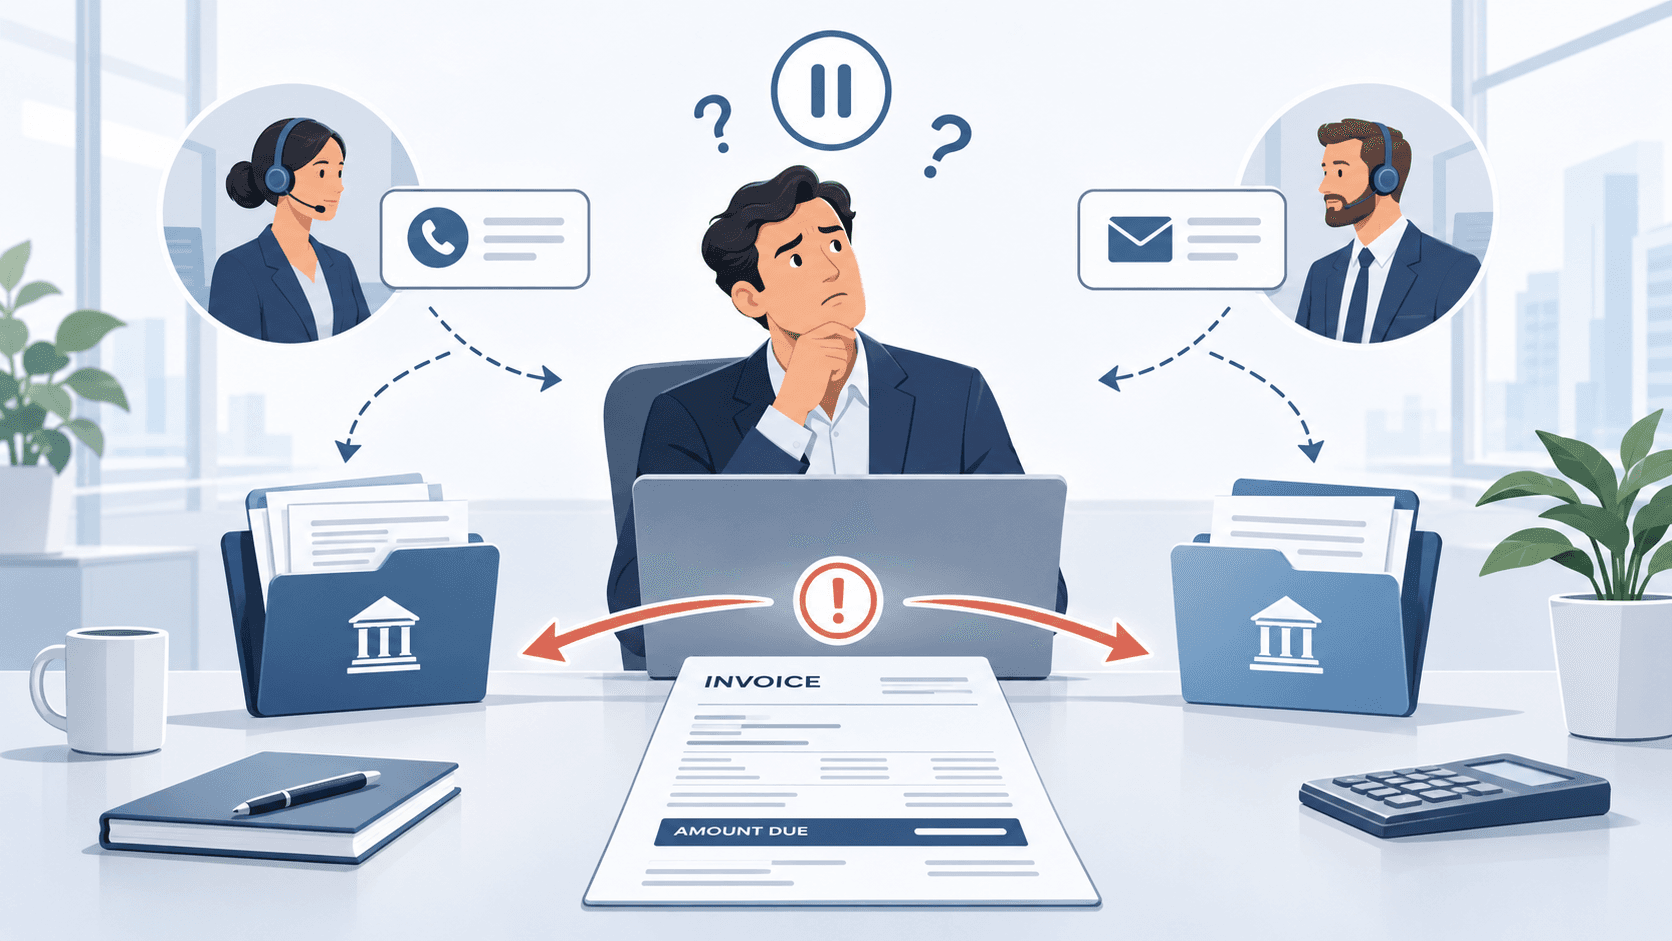
Both may be authorized to accept payment, and paying either one could resolve the debt. What he has no way to see from outside is whether they are working from the same balance and the same payment terms. If one agency agrees to let him pay the $20,000 over four months while the other demands the full amount by Friday, which arrangement counts? Only you can answer that.
A debtor who was ready to pay now has a sensible reason to wait until the numbers line up. A debtor who was looking for a reason to wait has just been given one. Either way, the extra effort has produced a pause.
The Day the Money Arrives
Suppose you clear up the confusion and the debtor agrees to pay the second agency $5,000 a month for four months. The second attempt paid off, and the checks start arriving.
The second agency set up the payment plan, so it bills its fee on each installment. The first agency spent four months on the letters and calls that came before that payment, and if its agreement entitles it to a fee on any payment made on accounts you placed with it, it bills too. Depending on how each contract is worded, you may owe two commissions on every $5,000 payment, and the lower rate that made the second agency attractive can disappear inside the duplicate fee.
If the first agency never heard about the payment plan, its next letter demands the full $20,000 from a debtor who has already paid half of it. The debtor now holds a demand that ignores the $10,000 he sent, and the account has to be reconciled with both agencies before it can get back on schedule.
If the debtor is also a current customer, the cost reaches the relationship. You wanted to show him you take the balance seriously. What he saw was two collectors who disagreed about what he owed.
Add it up and the headache can easily cost more than the lower rate saves.
What Your Agency Contracts Say
The Fair Debt Collection Practices Act (FDCPA), the primary federal law regulating consumer debt collection, does not apply to debts incurred for business purposes. No general federal prohibition stops a creditor from assigning the same commercial account to two agencies, though state laws and contractual restrictions may still apply. Much of what you read online about collection rules comes from that consumer framework, and your business receivables fall outside it. Of the limits that remain, the agreements you have already signed are often the more immediate concern.
Some placement agreements grant the agency exclusive authority over the accounts placed with it. Hand one of those accounts to a second agency and you may be in breach of the first agreement before the debtor has paid anything. Other agreements spell out when a commission is owed, sometimes including payments that arrive after an account is recalled, which is how competing commission claims arise.
A debtor who pays the second agency in month six may be paying because of the first agency's four months of letters, and the first agency can argue that every contact built toward that payment. The second agency can argue that it set up the plan the debtor is paying on. Who deserves the credit matters less than who is entitled to a commission under the agreements, so look at what each one says about payments received after recall, and specifically whether the original agency keeps a fee for a set period afterward, often called a tail period.
What to Do Instead
If you have decided to try another agency on an account, make sure the first agency's authority ends before the next agency's begins. Most of the headaches above trace back to two agencies holding authority over one account at the same moment. A clean handoff shrinks that overlap and gives you a chance to settle balances and fees before the next agency starts.
Before transferring an account:
- Review the existing agency agreement for recall provisions and any fees that survive termination.
- Send written recall instructions listing each account by name.
- Get written confirmation from the first agency that the account is closed and all collection activity has stopped, and hold the file until that confirmation arrives.
- Reconcile any payments or payment arrangements still in progress, including commissions owed.
- Once the closure confirmation is in hand, give the new agency an accurate account history and confirm its authority to begin.
Even after a clean recall, the debtor may still have the first agency's payment address from months of letters, and he can easily send his check there after the account has moved. The first agency is now holding money on an account it no longer works, while the new agency keeps asking the debtor for a balance he believes he paid. Your closure confirmation should spell out how quickly the first agency forwards any payment it receives after recall, and whether it claims a fee on that money. The new agency's first contact with the debtor should also make clear where payments go from now on.
For larger portfolios, check every new placement batch against accounts already assigned elsewhere. Duplicate placements can happen by accident when different departments or systems manage different slices of the receivables, and an old batch of write-offs can carry a live account along with it.
One Account, One Agency
Spreading a portfolio across several agencies means splitting the accounts themselves. One agency might take your accounts in the Southeast while another works the Midwest, or one might handle balances under $10,000 while another takes the larger files. Each debtor still hears from one collector, and after six months you can compare how each agency performed.
That comparison only holds up if you know what each agency was given. Account age is a big part of it. An invoice 90 days past due is a very different file from one that has sat for two years, and older accounts generally recover at lower rates no matter who works them. The story behind each account matters too, such as a disputed delivery or a balance that has already been through another agency. If one agency got the fresh accounts and another got the write-offs, the gap in their results may say more about the files than about the collectors. Note the age and history of each account before you place it, and give each agency a comparable mix so the results you compare reflect the work.
Giving a second agency a shot may even work. It can also leave a debtor waiting for the numbers to line up and two agencies billing for the same installments. If the first agency has run its course, replacing it gives the account the same fresh attempt and takes most of those headaches off the table. What you wanted from the second agency was a better chance of getting paid. More agencies on the account was only ever the means, and on a single balance it can work against the goal.
Read next
Your Team’s Role After Sending an Account to CollectionsNo matter how well a company manages receivables, one account will outlast its internal efforts. What happens inside the company after placement decides whether the agency can collect it.Have an account ready to place?
We work on contingency. No upfront cost.
JSD has been handling commercial collections since 1997. Every placement is reviewed by our team. Most clients are up and running the same day.