B2B Collections
B2B collections for unpaid business invoices
B2B (business-to-business) collections is the recovery of money one business owes another for goods or services sold on credit terms. JSD has handled commercial collections since 1997, on company-to-company accounts only, with a contingency fee drawn from what we recover.
IACC Sustaining Member and BBB A+ rated, serving businesses since 1997.
How an engagement works
- Contingency fee
- 10–50%
- Of what we recover, set by account age and balance.
- First contact
- 24–48 hrs
- After a single-account placement is verified.
- Remittances
- Biweekly
- Tuesdays, from a separate trust account.
- Established
- 1997
- Business-to-business accounts only, in the U.S. and abroad.
What It Means
What B2B collections covers
In B2B collections the debtor is a company. A distributor ships on net-30 terms, or a staffing firm bills for hours already worked, and the customer on the other end stops paying. Recovering that balance is what people mean by B2B debt collection. Credit managers also call it commercial collections or company-to-company collections, and the work is the same under every name.
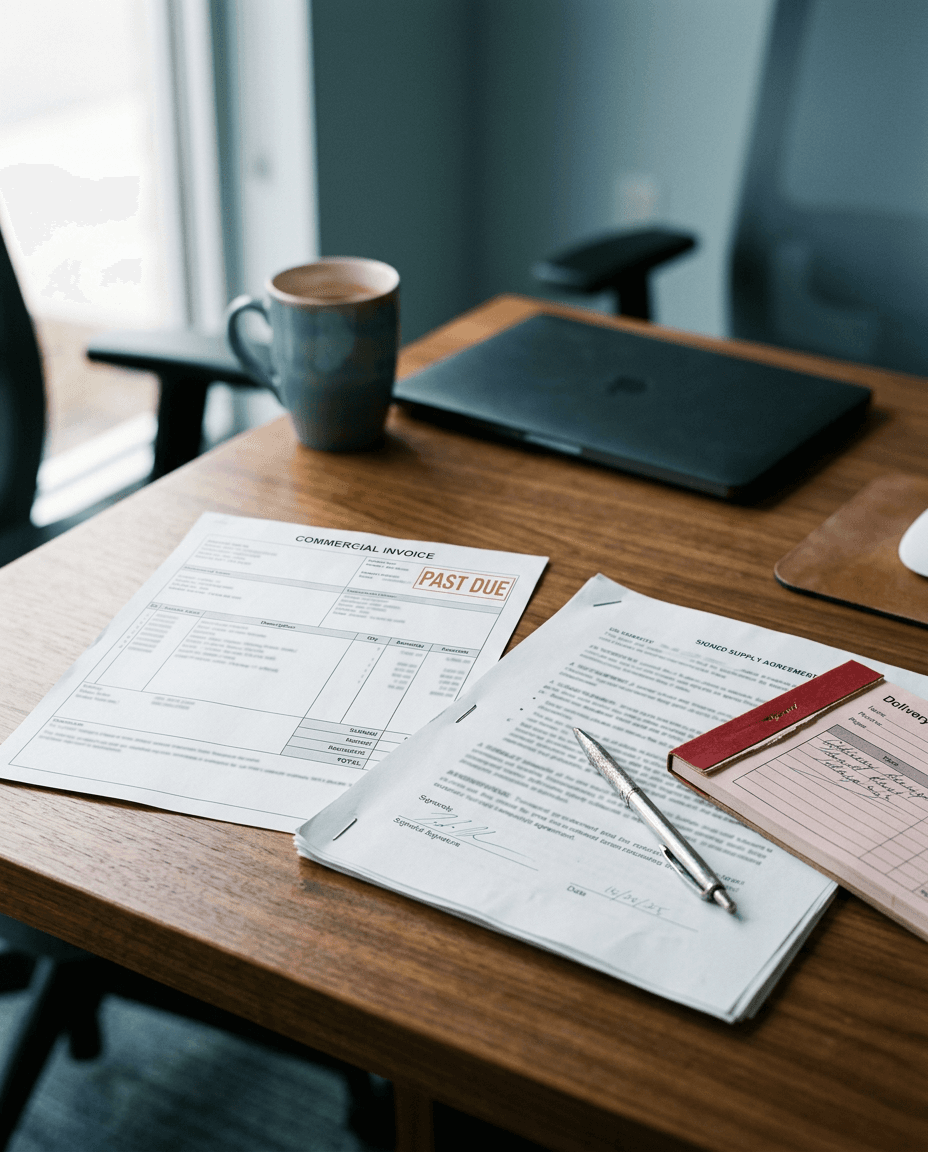
An unpaid B2B invoice carries its own paper history: a signed agreement, delivery records, and often years of orders. B2B receivables collection, or B2B accounts receivable collection, works from that paperwork. A customer who disputes the balance is answered with what the contract says, and a customer who simply stopped paying is reminded of terms they once accepted.
The paper trail behind a B2B invoice
- Signed agreement
- The terms the debtor accepted when the account opened.
- Delivery records
- Proof the goods or services reached the customer.
- Purchase orders
- The order the invoice answers to.
- Order history
- Often years of orders that were paid on time.
B2B vs. B2C
How B2B debt collection differs from B2C debt collection
B2C debt collection recovers money individuals owe for personal or household purposes, and in the United States it is governed largely by the Fair Debt Collection Practices Act. That act generally applies to covered consumer debts, not commercial ones, so B2B debt collection laws come from elsewhere. Other federal and state requirements still apply.
| Topic | B2C collections | B2B collections |
|---|---|---|
| Who owes the money | An individual, for personal or household purposes. | A company, for goods or services sold on credit terms. |
| Paper trail | A credit or loan agreement and account statements, held by the original lender. | Signed agreement, delivery records, purchase orders, and order history. |
| What governs it | The Fair Debt Collection Practices Act for covered debts, plus other federal and state consumer rules. | The contract between the businesses, commercial law on judgments and liens, state licensing and bonding rules for commercial agencies, and calling and texting rules such as the TCPA. |
| Who we reach | The individual. | Someone in accounts payable, or the owner, who knows the invoice exists. |
The difference shows up on the phone. A B2B debt collector reaches someone in accounts payable or the owner, a person who knows the invoice exists and has a reason for holding it. The conversation turns on the agreement and the delivery, and both companies usually have a relationship worth keeping. For a longer walk through the process, see what commercial debt collection is.
The size of the balance does not change the category. A single invoice from a small supplier is small business debt collection, and a customer based outside the United States is handled through international collections. Both are B2B work done by the same collectors.
B2B Collection Services
B2B collection services from the first late invoice to legal action
Most B2B collection agencies begin when an account is placed with them. JSD's B2B collection services also cover the stretch before placement, while the invoice is still young, and the stretch after a debtor has stopped answering a collector.
First-party AR under your name
Before an account goes to collections, JSD can work your past-due invoices under your logo as an extension of your receivables team. Your customer hears from your company, on a follow-up schedule your staff no longer has to keep.
Compare AR automation and an agencyThird-party B2B debt collection
Once internal reminders stop producing payments, the account is placed with JSD. A call from outside the relationship tells the customer the balance has moved to the top of someone's desk.
See commercial collectionsAttorney demand letter
A demand on attorney letterhead from JSD's network of outside commercial collection attorneys often moves a debtor who has ignored every invoice reminder. You decide afterward whether the account goes further.
Read about the 10-day demand letterLitigation referral
When an account needs suit, JSD explains why and what it is likely to cost, and nothing is filed until you approve it. Court and filing costs are yours, agreed in advance.
Follow the full recovery process
The Process
How JSD's B2B debt collectors work an account
Contact details on a placement file were usually written down when the customer first opened the account, and they have aged as long as the invoice. So the work starts before a collector dials, with verification and skip tracing.
JSD placement file research
37.4%
of supplied phone numbers reached the expected business on one attempt.
Based on JSD's review of 805 phone numbers supplied with commercial placements.
Read the agreement and verify the file
We read the contract or purchase order to learn how you bill, then call every number on the placement to see what it still reaches.
Find the person who can approve payment
Research covers who runs the company and who controls payables, so the collector calls a decision maker with the balance already in hand.
Talk it through with your customer
A JSD collector speaks with the customer directly, hears why the invoice went unpaid, and works from the terms they signed.
Resolve the balance and remit
Payment in full, or a payment plan the collector tracks installment by installment. Settlements below the full balance need your approval or a standing authority you set.
Each month you get a report splitting your placed accounts into open and closed, and online access shows where every account stands between reports. Recovered funds sit in a trust account until they are remitted, which the payments and remittances page explains in full.
Ready to place an account? The getting started guide lists what to send and how, or you can use the placement form directly.
Contingency fee
10–50%
Of what we recover.
- Fee applies only to recovered money.
- Set mostly by account age and balance.
- Newer accounts and larger balances fall toward the low end.
Fees
What B2B debt collection services cost
JSD works on contingency. The fee is a percentage of what we recover, between 10% and 50%, and it is set mostly by the age of the account and the size of the balance. Newer accounts and larger balances fall toward the low end. A customer who went past due last month still treats the invoice as current business, while one who has ignored it for a year has usually settled on what they think they owe, and moving that customer takes far more contact.
Standard collection work carries a fee only on recovered money. If your customer pays you directly after placement, the payment counts toward the recovery and the fee applies. If your contract or invoice terms make the customer responsible for collection costs, send the agreement with the placement and we pursue those costs along with the balance. For how rates compare across the industry, see how much collection agencies charge, or put numbers on your own receivables with the A/R calculator.
Client result
“After having had a few horrific experiences with past agencies I was able to find JSD, in which they have collected on 3 accounts that I had completely written off.”
Have an invoice you have already written off?
Send it for review. You pay a fee only on money we recover.
Request an account reviewTiming
When a B2B account belongs with a collection agency
Your own team should handle fresh invoices. The trouble starts when the same reminders keep going out and nothing comes back, because every deadline you extend without consequence tells the customer how seriously you take the balance. Collection can take a single day or around three months, and accounts placed within the first few months past due resolve fastest.
More on this in when to place an account, the vital warning signs of a customer in trouble, and how receivables stall.
Signs an account is ready for an agency
- A check has been promised more than once and the date keeps moving.
- Calls and emails that used to get answered now go nowhere.
- The balance is tied up in a disagreement your own back-and-forth has failed to settle.
- You hear that other vendors are waiting on the same customer.
Industries
B2B collections by industry
Each industry bills differently and each one produces its own kind of unpaid invoice. These pages cover how JSD collects for companies in each.
Account Review
Tell us which invoice went unpaid
Send the account and how long your team has been trying to collect it. We review it and reach out within one business day with a clear next step. Placing it stays your decision.
JSD is an IACC Sustaining Member, and its leadership includes a CLLA-certified member.
IACC member and BBB A+ rated since 1997.
FAQ
B2B collections questions
What is B2B collections?
B2B collections is the recovery of past-due invoices that one business owes another for goods or services sold on credit terms. The debtor is a company, so the work runs on the contract between the two businesses and is also called commercial collections or company-to-company collections.
What does a B2B debt collection agency do?
A B2B debt collection agency takes over a past-due commercial account once your own follow-up has stopped working. JSD verifies the debtor's contact details and finds the person who can authorize payment. The collector then works with that person toward payment in full or a payment plan. Recovered funds are held in a trust account and remitted to you every two weeks.
How is B2B debt collection different from B2C debt collection?
B2C debt collection recovers money individuals owe for personal or household purposes and falls under the Fair Debt Collection Practices Act. B2B debt collection recovers money one business owes another. That act generally applies to covered consumer debts and not to commercial ones, so commercial collection runs mainly on the contract terms, commercial law on judgments and liens, the licensing and bonding rules some states set for commercial agencies, and calling and texting rules such as the TCPA.
How much do B2B debt collectors charge?
JSD charges a contingency fee of 10% to 50% of the money it recovers. The rate depends mostly on how old the account is and how large the balance is, and newer accounts with larger balances fall toward the lower end. Fees apply only to recovered money.
Will using a B2B collection agency damage my customer relationship?
That depends almost entirely on who makes the call and how. A customer contacted professionally, with the account history in hand and a clear way to settle, usually keeps doing business with you once the balance is resolved. JSD represents your company the way we would want our own represented.
What do I need to place a B2B account?
Four things: the business name, the address, the amount owed, and the invoice date. An invoice, contract, purchase order, or email chain works as backup. Most clients place by email, and JSD handles the data entry and sends a placement confirmation the following day.
How long does B2B debt collection take?
Anywhere from a single day to around three months, depending on the debtor's situation and how long the account sat before placement. Accounts placed within the first few months past due resolve fastest, because the debtor still treats the invoice as current business.
Can you work our past-due accounts under our company name?
Yes. Through JSD's first-party AR service, past-due accounts are worked under your logo as an extension of your own receivables team, before an account ever goes to collections.
Does JSD handle international B2B collections?
Yes, in-house. Foreign placements go to the same collectors under the same fee agreement as domestic accounts, and currency is arranged case by case.
Is there a minimum balance for B2B collections?
JSD accepts single accounts of any size. Balances under $200 are generally a poor fit for contingency collection, and we will tell you so before you place one.
More answers in the commercial collections FAQ.
Resources
Guides for credit and AR teams
Further reading for choosing an agency, preparing a placement and understanding what happens after one is made.
Choosing an agency
- What to look for in a commercial collection agencyThe questions worth asking before you hand an account to anyone.
- Collection agency for unpaid invoicesHow an agency approaches a single past-due business invoice.
- Debt buyer vs. collection agencyWho owns the account, who gets paid and what that means for you.
Before and after you place
- The stigma around commercial debt collectionWhy the reputation exists, why it rarely applies to B2B recovery and why it still helps.
- Sending accounts to collections: internal supportGetting sales and finance aligned before an account is placed.
- 10-day demand letterA formal demand that often moves an account before it goes further.
- When a collection agency contacts your businessWhat to expect if you are on the receiving end of a B2B collection call.